

Business to Business (B2B) for sale in Australia
- Commercial Contractor Businesses1
- Commercial Heating Businesses2
- HR Service Businesses1
- Promotional product Businesses2
- Marketing and Advertising Businesses4
- Bookkeeping Businesses15
- Import Export Businesses5
- Industrial Cleaning Businesses9
- Scaffolding Hire Businesses1
- Equipment Rental Businesses5
- Waste Management Businesses1
- Plant Hire Businesses2
 Premium Commercial Cleaning & Janitorial Supply Business #421Brisbane QLDView moreAsking price:AUD $369 000
 Commercial Cleaning Business - Bunbury, WADalyellup WAView moreAsking price:AUD $299 000
 Established 30+ Year Import&Wholesale Business - Homewares, Gifts & Hospitality - QLDBrisbane Region, QLDView moreAsking price:AUD $249 000
 Major Educational Product Importer, Wholesaler/Distributor and Direct Online Supplier #422Sydney NSWView moreAsking price:AUD $2 190 000
 Import Wholesale Distribution - Renowned Product RangesGold Coast Region, QLDView moreAsking price:AUD $349 000
 Trusted Cinema & Photography Rental Business - Est. 15+ Years (Our Ref: V2111)Melbourne VICView moreAsking price:AUD $2 950 000
 37081 - Agritourism Booking Platform National Growth PotentialBrisbane Region, QLDView moreAsking price:AUD $199 000
 37081 - Agritourism Booking Platform National Growth PotentialPerth Region, WAView moreAsking price:AUD $199 000
 37081 - Agritourism Booking Platform National Growth PotentialMelbourne Region, VICView moreAsking price:AUD $199 000
 37081 - Agritourism Booking Platform National Growth PotentialSydney Region, NSWView moreAsking price:AUD $199 000
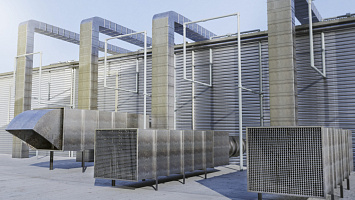 High-Margin HVAC & Industrial Dust Extraction Brendale, QLDBrendale QLDView moreAsking price:AUD $569 000
 Profitable, Fully Remote Bookkeeping and BAS PracticeSydney NSWView moreAsking price:AUD $798 000
 Corporate Promo B2B Business with Freehold - Newcastle area.Newcastle NSWView moreAsking price:AUD $1 900 000
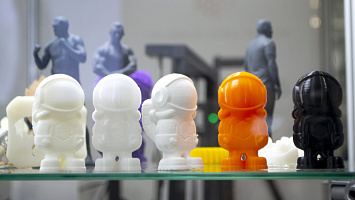 Full-Colour 3D Figurine Production SetupAdelaide Region, SAView moreAsking price:AUD $65 000
 Premium Commercial Cleaning & Janitorial Supply Business #421Brisbane QLDView moreAsking price:AUD $459 000
 High-Margin HVAC & Industrial Dust Extraction Brendale, QLDBrendale QLDView moreAsking price:AUD $569 000
 Commercial Cleaning sites - Macarthur DistrictNarellan NSWView moreAsking price:AUD $115 000
 Plant & Equipment Hire in CorowaCorowa NSWView moreAsking price:AUD $500 000
 Highly Profitable LED Screen Hire & Digital Signage BusinessNorthgate QLDView moreAsking price:AUD $1 334 000
- Well Established Accounting Firm For Sale Sydney 172 Active ClientsSydney NSWView moreAsking price:AUD $145 000
 Accounting Practice - North West Slopes NSWTamworth & North-West NSW Region, NSWView moreAsking price:AUD $850 000
 Accounting Firm For Sale Sydney 500,000 in fees per annumSydney NSWView moreAsking price:AUD $550 000
 UNDER OFFER - NICHE ACCOUNTING FEES – REAL ESTATE TRUST ACCOUNT AUDITS – Melbourne.Melbourne VICView moreAsking price:AUD $95 000
 Established Bookkeeping Business in Southern DownsBrisbane Region, QLDView moreAsking price:AUD $270 000
 35635 Profitable Bookkeeping Business - Ready for New OwnershipToowoomba & Darling Downs Region, QLDView moreAsking price:AUD $749 000
 Accounting Firm For Sale Sydney over 3000 active clientsSydney NSWView moreAsking price:AUD $450 000
 Accounting Practice - Mid North Coast NSW - $1.38MPort Macquarie & Mid North Coast Region, NSWView moreAsking price:AUD $1 380 000
 Accounting & Bookkeeping FranchiseAdelaide SAView moreAsking price:AUD $199 000
 Established Bookkeeping Practice - Reckon SpecialistPalmyra WAView moreAsking price:AUD $520 000
 Established Strata & Commercial Cleaning Business - Sunshine Coast & BrisbaneSunshine Coast Region, QLDView moreAsking price:AUD $299 000
 Specialised Commercial Cleaning Business with Repeat ClientsSunshine Coast Region, QLDView moreAsking price:AUD $385 000
 Commercial and Residential Installations - Net Profit of $400,000 - $500,000Gold Coast Region, QLDView moreAsking price:AUD $550 000
Business for sale by regions of Australia


FAQ
- Will the main customer contracts continue after the acquisition?Read assignment, change-of-control, termination, renewal, pricing, rebate and service-level clauses. Identify contracts requiring consent and speak with major customers at the agreed stage, because recurring invoices do not prove that revenue will survive a change of ownership.
- How should I measure customer concentration risk?Calculate revenue and gross margin by customer over several years, not only the latest period. Review churn, contract expiry, tender dates, pipeline quality and relationship ownership, then stress-test earnings if the largest customers reduce volumes or leave.
- What should I check in receivables and PPSR records?Age every receivable and examine disputes, credits, rebates, bad debts and post-balance-date collections. Search PPSR registrations over assets being acquired and review whether the business correctly registers retention-of-title or other security interests supporting customer credit.
- Can I review identifiable customer data during due diligence?Use de-identified or aggregated information wherever possible and control access through the confidentiality agreement and data room. OAIC guidance warns that prospective purchasers should avoid collecting unnecessary personal information and return or destroy it if the transaction fails.
- How do employment obligations affect a B2B acquisition?Identify employees, contractors, awards, enterprise agreements, accrued leave and superannuation. Australian transfer-of-business rules can preserve service and workplace instruments in some transactions, so allocate entitlements clearly and test whether contractor arrangements are genuinely independent.
- How can I verify recurring B2B earnings?Reconcile contracts and invoices to BAS, bank receipts and accounting records. Separate contracted recurring revenue from projects, pass-through costs and related-party sales, then adjust for unbilled work, deferred income, doubtful debts and seller relationships that may not transfer.